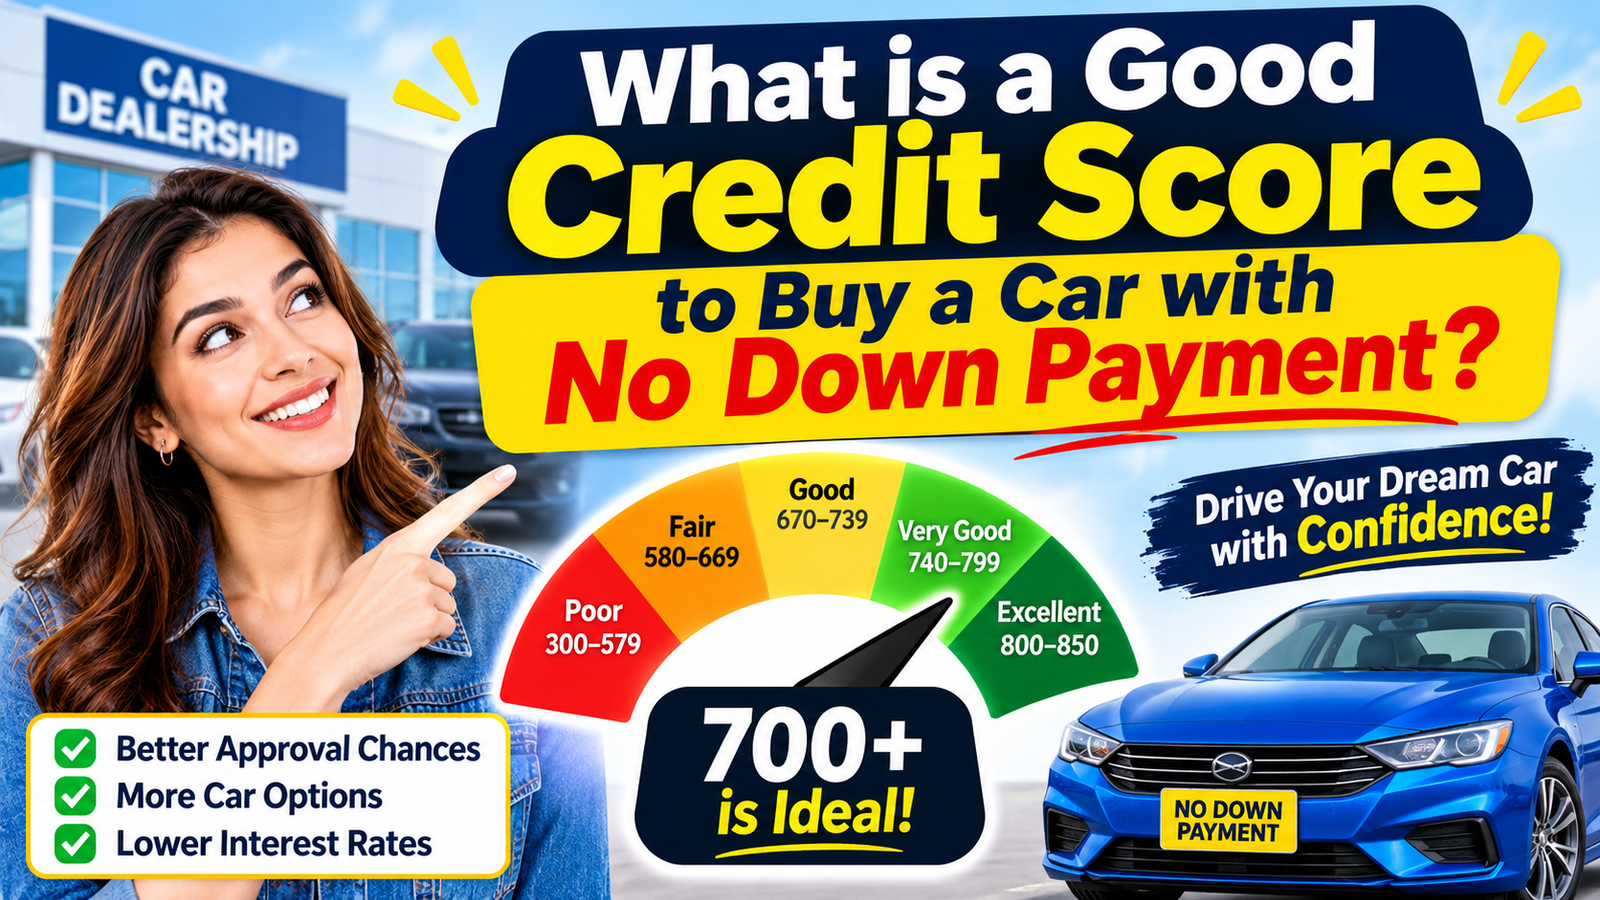
What Is a Good Credit Score to Buy a Car With No Down Payment?
Buying a car without making a down payment can be convenient when you need a vehicle but do not have enough savings available upfront. However, getting approved for a zero-down auto loan may be more challenging than qualifying for traditional car financing. Lenders often consider your credit history, income, existing debts, employment stability, and the total amount you want to borrow before approving an application.
A strong credit profile can make the process easier and help you qualify for better interest rates. Understanding what is a good credit score to buy a car with no down payment can help you prepare before visiting a dealership or applying for financing.
In the United States, FICO scores generally range from 300 to 850. Although there is no universal minimum score for a car loan, borrowers with higher scores typically have more financing options. A score of 670 or above is a useful starting point, while 740 or higher may put you in a stronger position to qualify for favorable terms.
What Credit Score Do You Need for a No-Down-Payment Car Loan?
There is no fixed credit score requirement for financing a vehicle without a down payment. Every bank, credit union, dealership financing company, and online lender has its own approval criteria. Some lenders may approve borrowers with fair credit, while others may require a stronger credit history for zero-down financing.
Generally, a credit score of 700 or higher can improve your chances of qualifying for a car loan without an upfront payment. However, your credit score is only one part of the application.
Lenders also want to know whether your monthly income is sufficient to cover the proposed car payment and your other financial responsibilities. If your income is stable and your existing debt is manageable, you may have a stronger application even if your score is not excellent.
Understanding Credit Score Categories
The following table provides a general overview of FICO credit score ranges and how they may affect auto financing.
| FICO Score Range | Credit Category | General Financing Outlook |
| 800–850 | Exceptional | Strong potential for competitive offers |
| 740–799 | Very Good | Good position for favorable loan terms |
| 670–739 | Good | May qualify for several financing options |
| 580–669 | Fair | Approval possible, but rates may be higher |
| 300–579 | Poor | Limited options and potentially expensive financing |
These categories are general guidelines, not guaranteed lender requirements. A lender may use a different scoring model, including an industry-specific FICO Auto Score.
Why Do Lenders Prefer Higher Credit Scores for Zero-Down Financing?
A down payment reduces the amount of money a lender needs to finance. When you make an upfront payment, you immediately reduce the loan balance and demonstrate that you have funds available for the purchase.
Without a down payment, the lender finances the entire eligible purchase amount, which can increase its risk. If the borrower stops making payments, the vehicle may be worth less than the remaining loan balance.
This is one reason lenders may prefer applicants with stronger credit histories when considering no-money-down applications.
Lower Lending Risk
A higher credit score generally indicates a history of managing credit responsibly. Borrowers who consistently make payments on time and maintain manageable credit balances may appear less risky to lenders.
Better Repayment History
Your previous loan and credit card payments help lenders understand how you handle financial obligations. A history of on-time payments can strengthen your application.
More Competitive Financing Options
Applicants with strong credit may qualify for more attractive interest rates, longer financing options, or promotional offers, depending on the lender and vehicle.
Factors That Matter Beyond Your Credit Score
Even if you have a credit score of 740 or higher, approval for a zero-down auto loan is not guaranteed. Lenders evaluate several financial details before making a decision.
Monthly Income
Your income helps lenders determine whether you can comfortably afford the monthly car payment. A consistent income from employment, self-employment, or another reliable source can support your application.
Debt-to-Income Ratio
Your debt-to-income ratio compares your monthly debt payments with your gross monthly income. If a large portion of your income already goes toward credit cards, personal loans, student loans, or housing costs, a lender may consider another loan too expensive.
Employment Stability
A stable employment history can demonstrate that you have a reliable source of income. Some lenders may request recent pay stubs, employment information, or bank statements to verify your financial situation.
Credit History
Lenders may review more than your credit score. They can examine missed payments, collections, previous auto loans, bankruptcies, and other details in your credit report.
Vehicle Price and Loan Amount
The price of the vehicle directly affects how much financing you need. A less expensive car may be easier to finance without a down payment because the overall loan amount is lower.
Can You Buy a Car With No Down Payment and a 600 Credit Score?
Yes, it may be possible to buy a car with a 600 credit score and no down payment, but your options could be limited.
A score around 600 generally falls within the fair or nonprime range, depending on the scoring model. Some lenders specialize in financing borrowers with lower credit scores, but they may charge higher interest rates or impose additional requirements.
For example, a lender might approve your application if you have a steady income, manageable monthly debt, and a reasonable vehicle purchase price. Another lender may require a down payment or a qualified co-signer.
Before accepting an offer, compare the annual percentage rate (APR), loan duration, monthly payment, and total interest. A loan that appears affordable because of a low monthly payment could become expensive if the repayment period is too long.
How to Improve Your Chances of Getting Approved With No Money Down
If you want to finance a car without paying anything upfront, preparing your finances before applying can improve your chances.
Check Your Credit Reports
Review your credit reports from Equifax, Experian, and TransUnion. Look for incorrect account balances, unfamiliar accounts, inaccurate late payments, or other mistakes. You can dispute information that is incorrect or incomplete.
Pay All Bills on Time
Payment history is an important factor in many credit scoring models. Make your credit card, loan, and other required payments by their due dates. Setting up automatic payments or reminders can help prevent missed payments.
Reduce Credit Card Balances
High credit card utilization can negatively affect your credit score. Paying down outstanding balances may improve your credit profile over time.
Avoid Applying for Multiple Loans
Submitting several credit applications within a short period can create unnecessary hard inquiries. Although certain auto loan inquiries made during a rate-shopping period may be grouped together by scoring models, you should still compare lenders carefully.
Choose an Affordable Vehicle
A lower-priced vehicle may require less financing and create a more manageable monthly payment. Avoid choosing a car based only on its appearance or advertised payment amount.
Consider a Co-Signer
If your credit history is limited or your score is lower, a qualified co-signer may strengthen your application. However, the co-signer becomes legally responsible for the debt if you fail to make payments.
What Are the Risks of Buying a Car With No Down Payment?
Zero-down financing can help you purchase a vehicle without using your savings immediately. However, it also comes with financial risks that you should understand before signing a loan agreement.
Higher Monthly Payments
When you finance the full eligible purchase amount, your monthly payments may be higher than they would be with a down payment. The exact amount depends on the vehicle price, APR, and loan term.
Negative Equity
One of the biggest risks is negative equity, sometimes called being upside down on a car loan. This happens when you owe more on the loan than the vehicle is worth.
Cars generally lose value over time. If you finance the entire purchase price, depreciation can leave you owing more than the car’s market value, especially during the early years of the loan.
Higher Interest Costs
If your credit score is not strong, the lender may offer a higher APR. Financing the entire vehicle price at a high interest rate can significantly increase the total cost of ownership.
Additional Insurance Considerations
Some lenders require comprehensive and collision coverage throughout the loan period. You should include insurance costs in your budget rather than focusing only on the monthly loan payment.
How Much Credit Score Do You Need for Different Car Financing Options?
The credit score you need can depend on whether you are purchasing a new or used vehicle and which financing program you choose.
New-car financing may include manufacturer promotions for qualified buyers. These offers sometimes feature low or even zero-percent APR, but they generally require strong credit and may have restrictions.
Used-car financing can have different requirements because vehicle age, mileage, condition, and resale value also matter.
A borrower with a score above 740 may have access to more competitive financing opportunities, while someone with a score between 600 and 669 may need to compare more lenders.
The following ranges are general planning guidelines, not official approval thresholds:
| Credit Score | General Financing Position |
| 780 and above | Strong credit profile |
| 740–779 | Very good financing position |
| 670–739 | Good starting point |
| 600–669 | Some lenders may consider the application |
| Below 600 | Specialized financing may be necessary |
Remember that lenders can use different credit models and evaluate your complete financial situation.
Steps to Take Before Applying for a Zero-Down Auto Loan
Preparing before visiting a dealership can help you avoid unnecessary expenses and make a more informed decision.
Set a Realistic Budget
Calculate how much you can afford to spend each month. Include the car payment, insurance, fuel, maintenance, registration, and other ownership expenses.
Get Prequalified
Consider checking prequalification options with banks, credit unions, and online auto lenders. Prequalification may help you understand potential loan terms without immediately submitting a full application. Confirm whether the lender uses a soft or hard credit inquiry.
Compare Multiple Offers
Do not accept the first financing offer you receive. Compare APR, loan length, fees, and total repayment costs. A lower monthly payment does not always mean a cheaper loan.
Read the Financing Agreement
Review the complete loan agreement before signing. Check for additional fees, optional products, early payment conditions, and any requirements related to insurance.
Keep Some Emergency Savings
Even if you qualify for zero-down financing, having money available for unexpected repairs, insurance deductibles, and other expenses can protect your financial stability.
Conclusion
A credit score of 700 or higher can put you in a stronger position when applying for a car loan with no down payment. However, there is no universal score that guarantees approval. Lenders also evaluate income, employment stability, existing debt, payment history, and the vehicle’s value. Before accepting zero-down financing, compare multiple offers and calculate the total borrowing cost. A strong credit profile and a realistic budget can help you find a vehicle that fits your financial situation without creating unnecessary long-term debt.
Frequently Asked Questions
1. What is the best credit score to buy a car with no down payment?
A score of 740 or higher can put you in a strong position for competitive auto financing. However, lenders also consider your income, debt, credit history, and vehicle price before approving a zero-down loan.
2. Can I get a car with no money down and a 650 credit score?
Yes, some lenders may approve applicants with a 650 credit score. However, you may face higher interest rates or additional requirements depending on your financial profile.
3. Does a 700 credit score guarantee a zero-down car loan?
No. A 700 credit score can improve your approval chances, but lenders also review your income, employment, existing debt, and ability to make monthly payments.
4. Is buying a car with no down payment a good idea?
It can be useful if you need a vehicle and have enough income to manage the payments. However, you may pay more interest and face a greater risk of negative equity because you are financing the full eligible purchase amount.
5. Can I get a zero-down auto loan with bad credit?
Some specialized lenders offer auto financing to borrowers with bad credit. Approval depends on the lender’s requirements and your overall financial situation. You may need a co-signer, stable income, or other qualifying factors, and the interest rate could be higher.
One thought on “What Is a Good Credit Score to Buy a Car With No Down Payment?”